Introduction
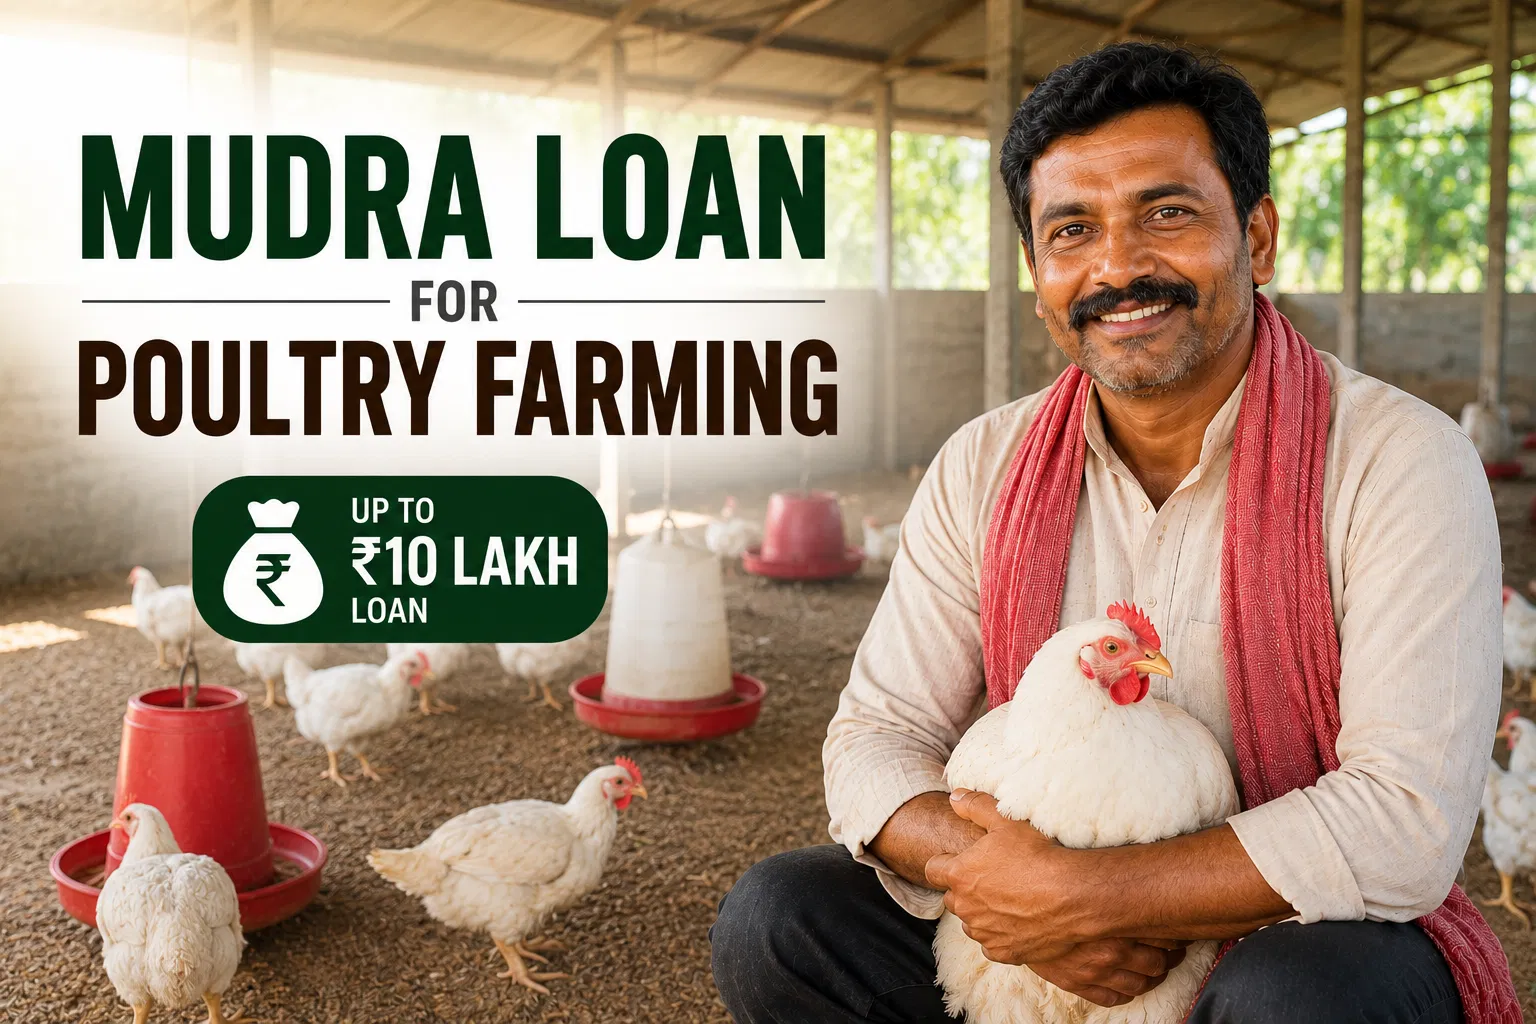
Poultry farming — whether broiler (meat) or layer (egg) production — is one of the most common agri-allied businesses financed through Mudra loans, since it typically needs a moderate upfront investment in shed, day-old chicks, and feed rather than land purchase. Poultry is explicitly listed among Mudra's eligible allied-agriculture activities, and around 60% of Mudra poultry disbursals go toward setting up entirely new units. This guide walks through realistic project costs, loan tiers, and the application process.
Mudra Poultry Loan Overview
- Maximum Loan Amount — Up to ₹10 lakh under standard tiers; up to ₹20 lakh under Tarun Plus for repeat, well-repaid Tarun borrowers
- Collateral — None required up to ₹1.6 lakh; above this, lender-specific collateral or guarantee norms apply
- Typical Broiler Unit Sizing — A 1,000-bird broiler unit typically costs roughly ₹2.5–3.5 lakh including shed, equipment, and first batch of chicks, fitting within the Kishore or lower Tarun tier
- Typical Layer Unit Sizing — Layer units generally need a larger minimum batch size and higher working capital, often requiring Tarun-tier or larger financing
- Other Complementary Schemes — NABARD's Poultry Development Scheme (25%, up to 33% for SC/ST/NE, capital subsidy) and AHIDF for larger processing-linked poultry infrastructure
Objectives of the Poultry-Focused Mudra Loan
- Provide collateral-free credit for setting up or expanding a broiler or layer poultry unit.
- Support first-generation poultry entrepreneurs, including agriculture graduates and rural youth.
- Fund the full cycle — shed construction, equipment, day-old chicks, feed, and basic biosecurity/veterinary costs.
- Enable both independent farming and contract farming models tied to integrator companies.
Loan Amount and Eligible Uses
- Shed construction — for a 1,000-bird broiler unit, typically around ₹2 lakh for a roughly 500 sq ft shed.
- Equipment — feeders, drinkers, brooders, ventilation fans, and heaters, typically ₹50,000–₹80,000 for a small unit.
- Day-old chicks (DOC) and the first batch of feed, medicine, and electricity costs.
- Working capital for recurring batches, manageable through the MUDRA Card for flexible drawals.
- Bird insurance is often recommended before disbursal, particularly for larger flocks.
Broiler vs Layer: What Changes for Financing
- Broiler units cycle faster (6–8 weeks per batch, 7–8 batches a year), so working capital needs recur more often but each batch is smaller in scale.
- Layer units need a longer initial investment horizon before egg production stabilises, and lenders often expect a higher minimum batch size — commonly cited around 10,000 birds for a dedicated layer farm — pushing many layer projects into Tarun or beyond.
- Both models can be financed under Mudra's Kishore/Tarun tiers, but a layer project of meaningful scale is more likely to need a NABARD-linked scheme (like the Poultry Development Scheme) layered alongside Mudra for the capital-subsidy component.
Benefits to Poultry Farmers
- Collateral-free credit for a business with a relatively short cash-flow cycle compared to many other agri-allied activities.
- Loan tiers that map naturally to a starter backyard unit (Shishu/Kishore) versus a larger commercial broiler or layer operation (Tarun/Tarun Plus).
- Priority-sector classification generally speeds up processing since poultry is a well-established agri-allied lending category for most banks.
- Can be combined with NABARD's Poultry Development Scheme subsidy or AHIDF for larger processing-linked investments.
Limitations to Consider
- Mudra itself carries no capital subsidy — the 25–33% subsidy some farmers reference comes from NABARD's separate Poultry Development Scheme, not from Mudra.
- Minimum flock-size expectations (commonly 2,000+ birds per cycle for broiler, much higher for layer) mean a very small backyard unit may not interest every lender for anything beyond a Shishu loan.
- Disease and mortality risk is real and not insured by default — bird insurance is a separate cost worth budgeting for.
- A realistic, bank-ready project report with per-batch cost and revenue projections is essential; overly optimistic DPRs are a common reason for rejection.
Documents Required
- Aadhaar Card and PAN Card
- Land ownership papers or a registered lease for the shed site (commonly required to be at least 500 metres from residential areas)
- Project report with bird count, shed design, feed cost, sales plan, and repayment schedule
- Quotations/invoices for shed construction and equipment (feeders, drinkers, borewell, water systems)
- Poultry farm registration/licence, where required by the state or local body
How to Apply for a Mudra Poultry Loan
- Decide on broiler or layer farming and estimate flock size based on available land, capital, and market access.
- Prepare a detailed project report with per-batch cost and revenue figures, plus an annual income projection.
- Approach an existing bank relationship first, or apply via the Udyamimitra/Jan Samarth portal, requesting the Kishore or Tarun Mudra category as appropriate.
- Be ready for a possible site visit by the bank to confirm location, land, and access before sanction.
- On disbursal, construct the shed, order day-old chicks, and begin the first batch, repaying EMIs on schedule.
Conclusion
A modest broiler unit is one of the more straightforward agri-allied businesses to finance through Mudra, largely because the shed and equipment costs fit comfortably within the Kishore or lower Tarun tier. Larger layer operations or processing-linked poultry ventures typically need to combine Mudra with a NABARD-backed subsidy scheme to make the numbers work — so it's worth mapping the project's real scale before choosing a financing route.
Disclaimer: Loan amounts, project costs, and eligibility criteria vary by lender, region, and market conditions, and are subject to change. Readers are advised to verify current details on the official MUDRA website (mudra.org.in) or with their nearest bank branch before applying or making any financial decision.